This blog post has been researched, edited, and approved by John Hanning and Brian Wages. Join our newsletter below.
Frequently Asked Questions
What is the Q3 estimated tax payment deadline?
For many taxpayers, the Q3 estimated tax payment deadline is September 15. Exact timing can depend on the taxpayer, entity type, fiscal year, and specific facts, so businesses should confirm deadlines with their tax advisor.
Can deductions or credits affect estimated tax payments?
Yes. Deductions and credits may affect taxable income, projected liability, and the larger tax planning picture.
What specialty tax opportunities should businesses review before Q3 estimated taxes?
Businesses may want to review cost segregation, R&D tax credits, fixed asset reviews, energy efficiency incentives, repair versus capitalization treatment, state tax credits, and accounting method opportunities.
Should a business wait until year-end to review specialty tax opportunities?
Not always. Waiting until year-end or tax filing season can make it harder to gather documentation, identify qualifying activity, and coordinate with a CPA.
Most businesses treat Q3 estimated taxes as a payment deadline.
They check income, look at cash flow, estimate what is due, make the payment, and move on.
But September is also a good time to ask another question:
Are there deductions, credits, or specialty tax opportunities that should be reviewed before the payment is finalized?
For many taxpayers, the third-quarter estimated tax payment deadline falls on September 15. That deadline can be a useful reminder for business owners and advisors to review activity from the year before heading into Q4.
The payment matters.
But the planning around the payment matters too.
If the business purchased property, completed renovations, invested in equipment, performed technical work, improved a building, trained employees, or expanded operations, there may be tax items worth reviewing before year-end.
Why Q3 Estimated Taxes Should Be More Than a Payment Deadline
Q3 estimated taxes are often handled quickly.
How much do we owe?
When is it due?
Do we have the cash available?
Those are important questions. But they are not the only questions to ask.
By September, a business may already have months of activity that could affect tax planning. A building may have been purchased. Equipment may have been placed in service. Renovations may be complete. Technical projects may be underway.
Employees may have been trained. Expansion plans may already be moving.
If those items are not reviewed until tax filing season, it may be harder to organize the details and understand what opportunities apply.
Q3 gives businesses a chance to pause before the year gets too far along.
What Specialty Tax Opportunities Could Affect the Bigger Tax Picture?
Specialty tax opportunities depend on the business, industry, activity, documentation, and tax situation.
For some businesses, the main issue may be depreciation. For others, it may be credits, incentives, fixed assets, or energy-efficient building improvements.
These areas become especially important when a business has had major activity during the year.
That may include buying property, improving a facility, developing a new product or process, training employees, expanding operations, or making large equipment purchases.
Cost Segregation After Property Purchases or Improvements
If a business purchased, built, renovated, expanded, or improved a property this year, cost segregation may be worth reviewing before year-end planning begins.
A cost segregation study looks at the property and helps identify whether certain building components may qualify for shorter depreciation periods.
This may apply after a commercial property purchase, tenant improvement project, facility expansion, renovation, or new construction project.
For example, a restaurant, medical building, manufacturing facility, office building, apartment property, or retail space may include assets that should not automatically be treated the same as the main building.
That does not mean every property is a fit.
The value depends on the property type, cost basis, documentation, placed-in-service timing, and tax situation. But if the activity happened earlier in the year, Q3 can be a good time to ask whether it should be reviewed.
Fixed Asset Reviews After Major Purchases
Businesses often buy equipment, make improvements, replace assets, or update facilities during the year.
Those costs may be entered into the accounting system quickly so the business can keep moving.
But asset classification matters.
A fixed asset review can help determine whether assets are being treated correctly, whether certain costs should be capitalized, whether old assets should be reviewed, and whether depreciation schedules need a closer look.
This can be especially important when a business has grown, renovated, upgraded equipment, or inherited old fixed asset records that may not tell the full story.
Q3 is a practical time to review this because there is still time to coordinate with the CPA before year-end planning becomes rushed.
R&D Tax Credits for Technical Work During the Year
Many businesses perform technical work without calling it research and development.
They may be improving a product, testing a process, developing software, solving engineering problems, improving manufacturing methods, or evaluating technical alternatives.
That work may be worth reviewing for the R&D tax credit.
The challenge is documentation.
By Q3, project details are usually still fresh. The business may still be able to identify who worked on the project, what technical problems were addressed, what alternatives were tested, and what records support the activity.
Waiting until tax filing season can make that harder.
People forget details. Project notes get buried. Time records may not tell the full story.
That is why businesses with technical activity should consider reviewing R&D credit eligibility before the end of the year.
Energy Efficiency Incentives and Building Improvements
If a business completed energy-efficient building improvements during the year, those projects may deserve a closer look.
Energy efficiency incentives may relate to commercial building systems such as lighting, HVAC, hot water systems, and the building envelope.
This can be relevant for businesses that built, renovated, upgraded, or improved commercial property.
Documentation matters here too.
Project records, energy models, invoices, drawings, specifications, and placed-in-service dates may all be important. Q3 can be a good time to gather those records before the project team moves on and the documents get harder to find.
State Tax Credits and Business Growth
Specialty tax planning is not limited to federal deductions and credits.
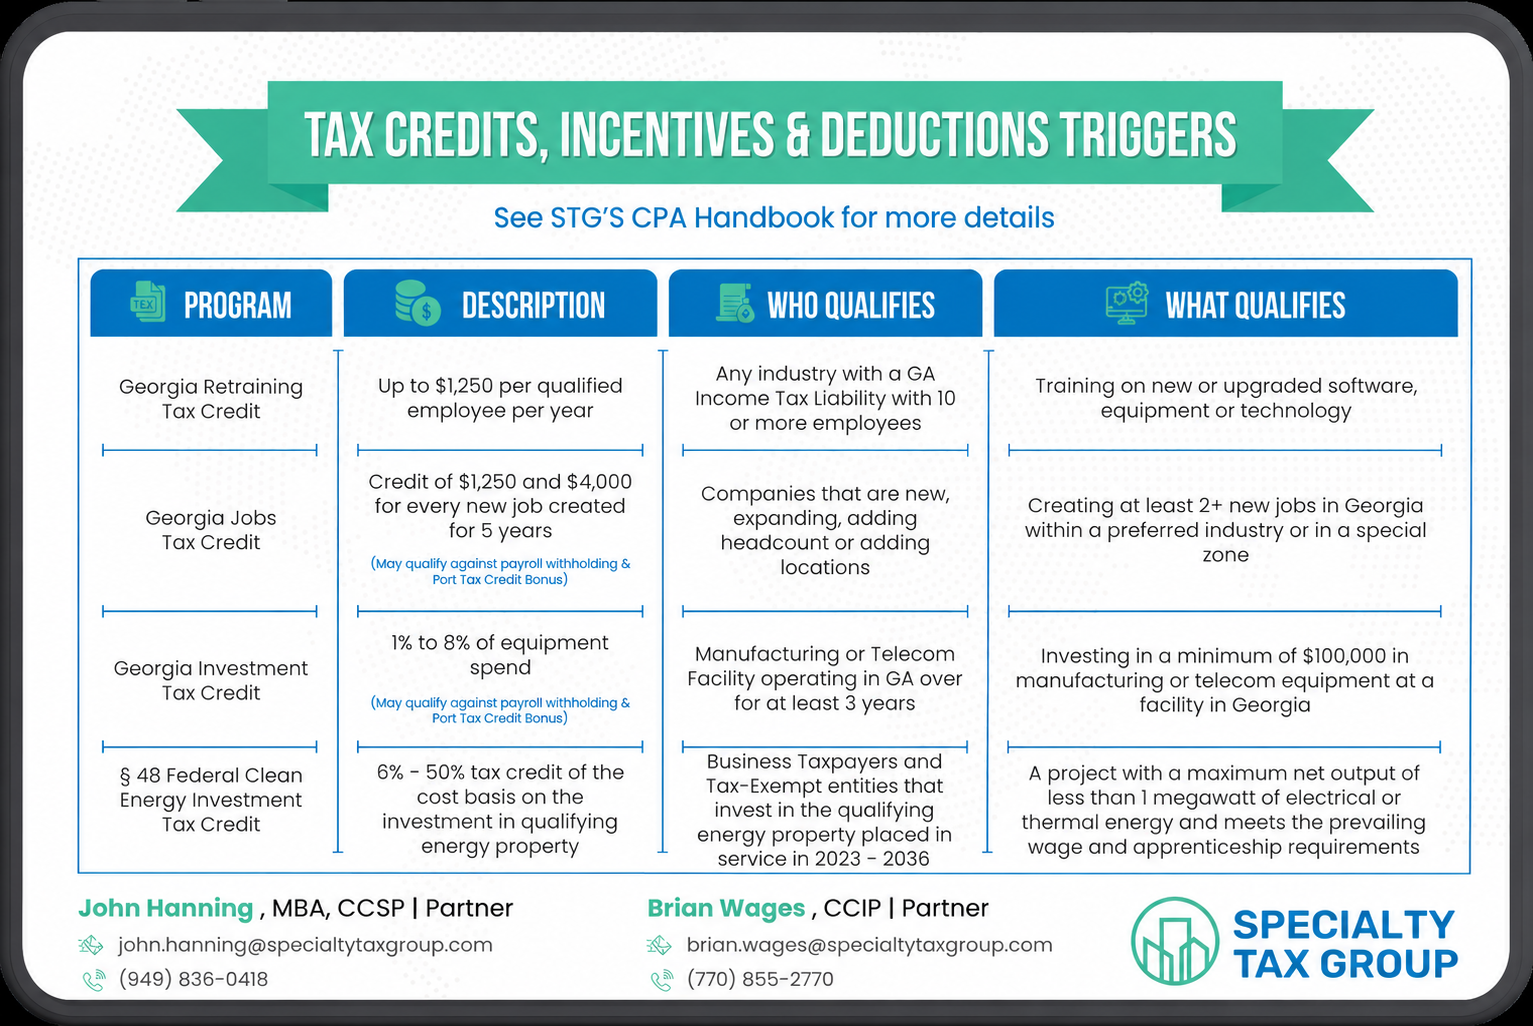
Some businesses may also have state tax credit opportunities tied to hiring, training, expansion, investment, or location decisions.
These credits can be easy to miss because they may not show up automatically during normal tax preparation.
A business may need to review whether it created jobs, trained employees, invested in a facility, expanded operations, or met state-specific requirements.
September is a useful time to look at these items because there is still part of the year left to gather records and review next steps.
Why Documentation Matters Before Year-End
A missed tax opportunity is not always missed because the business did not qualify.
Sometimes it is missed because the documentation was not organized.
That can happen with cost segregation, R&D tax credits, energy incentives, fixed asset reviews, repair studies, and state credits.
The business may have the activity, but the support may be spread across invoices, contracts, project folders, payroll records, time entries, emails, drawings, and accounting files.
By tax filing season, it can be harder to piece everything together.
Q3 gives businesses and advisors a chance to review the year before the year is over.
What Should Businesses Review Before Making a Q3 Estimated Tax Payment?
Before finalizing a Q3 estimated tax payment, businesses may want to ask:
- Did we purchase, build, renovate, or improve property this year?
- Did we place new equipment, systems, or building improvements in service?
- Did we complete tenant improvements or expand a facility?
- Did we perform technical work involving testing, modeling, engineering, software development, or process improvement?
- Did we train employees, add jobs, or expand into a new location?
- Did we complete energy-efficient upgrades to lighting, HVAC, hot water systems, or the building envelope?
- Did we review our fixed asset schedule for accuracy?
- Did we coordinate with our CPA on specialty tax items before estimating the payment?
Not every item will apply to every business.
But if the answer is yes to any of these questions, it may be worth taking a closer look.
How Specialty Tax Group Helps Businesses Review Specialty Tax Opportunities
Specialty Tax Group helps businesses and advisors review tax opportunities that may be missed during normal planning.
That can include cost segregation, R&D tax credits, fixed asset reviews, energy efficiency incentives, tangible property and repair reviews, accounting method considerations, and state tax credits.
For Q3 estimated tax planning, the goal is not to replace the CPA’s role or provide a generic estimated tax calculation.
The goal is to help identify whether the business had activity during the year that may affect the larger tax picture.
That includes reviewing what happened, what records are available, and whether a deeper specialty tax review may make sense before year-end.
Final Takeaway
Q3 estimated taxes are more than a payment deadline.
They can also be a reminder to review deductions, credits, and specialty tax opportunities before the year gets too far along.
If a business purchased property, completed renovations, invested in equipment, performed technical work, improved a building, trained employees, or expanded operations, those items may affect the broader tax conversation.
The payment still matters.
But the planning around the payment matters too.
Specialty Tax Group can help businesses and advisors review whether specialty tax opportunities may apply before year-end planning becomes a last-minute scramble.
2024 Tax Guide