This blog post has been researched, edited, and approved by John Hanning and Brian Wages. Join our newsletter below.
On
March 10, 2025, Representatives Ron Estes (R-KS) and John Larson (D-CT) introduced
H.R. 1990, the
American Innovation and R&D Competitiveness Act of 2025, to reinstate the immediate deductibility of research and experimental (R&E) expenses. This bipartisan bill aims to amend
Section 174 of the Internal Revenue Code, effectively reversing changes made by the 2017 Tax Cuts and Jobs Act (TCJA).
Background: From Deductibility to Amortization
Before the TCJA, U.S. businesses were allowed to fully deduct R&E costs in the year they were incurred, directly encouraging innovation and technological advancement.
However, the TCJA altered this approach. Beginning
January 1, 2022, companies were required to
amortize domestic R&E expenses over five years and
foreign R&E over 15 years, significantly increasing upfront costs and creating liquidity challenges for research-heavy firms (source).
Key Provisions of the Act
- Immediate Expensing Election
Businesses can elect to fully deduct R&E expenses in the year they are incurred, restoring the pre-TCJA treatment. - Optional Amortization
Taxpayers may choose to amortize R&E costs over at least 60 months, offering flexibility in tax planning. - Expenditure Exclusions
Costs tied to land acquisition, property improvements, and resource exploration (e.g., oil, gas, mining) are excluded from immediate expensing eligibility. - Coordination with Section 280C
The bill includes measures to prevent double-dipping, ensuring businesses don't receive both full deductions and R&D tax credits on the same expenditures. - Retroactive Application
The legislation would apply retroactively to tax years beginning after December 31, 2021, effectively reversing the amortization rules back to their implementation date (bill text).
Bipartisan Support and Legislative Status
The bill was referred to the House Committee on Ways and Means and has received strong bipartisan backing with 77 original cosponsors, including Rep. Suzan DelBene (D-WA) and Rep. Rudy Yakym (R-IN).
- "Research and development in the United States does more than just advance innovation—it provides good-paying jobs for Americans and strengthens our nation's competitive edge." — Rep. Ron Estes
Industry Response and Economic Impact
The bill has received broad praise from national industry leaders:
- The National Association of Manufacturers (NAM) and the Association of Equipment Manufacturers (AEM) both issued strong endorsements, citing its importance to
job creation,
technological leadership, and
domestic production.
- A coalition of life sciences associations, including California Life Sciences, BioFlorida, and BioCT, emphasized the bill’s importance to
biotech innovation and the development of
critical treatments and cures (BIO letter of support).
- For startups and SMEs, immediate expensing could significantly boost reinvestment in R&D, talent acquisition, and scale-up operations (source).
Looking Ahead
While the bill enjoys bipartisan and industry support, its path forward may hinge on inclusion in
year-end tax packages or broader tax reform. As of mid-April, the
Congressional Budget Office (CBO) has
not yet released a score for the bill, which may affect timing and strategy for final passage.
Conclusion
The American Innovation and R&D Competitiveness Act of 2025 offers a critical opportunity to restore a proven incentive for U.S. innovation. By reinstating immediate expensing, the bill supports the economy, helps companies bring new products to market faster, and sustains America's leadership in global technology and research.
Similar to previous legislation such as the American Innovation and Jobs Act, this bill addresses long-standing concerns from the business community while providing essential support for America's innovation ecosystem.
Need Guidance on How This Affects Your Business?
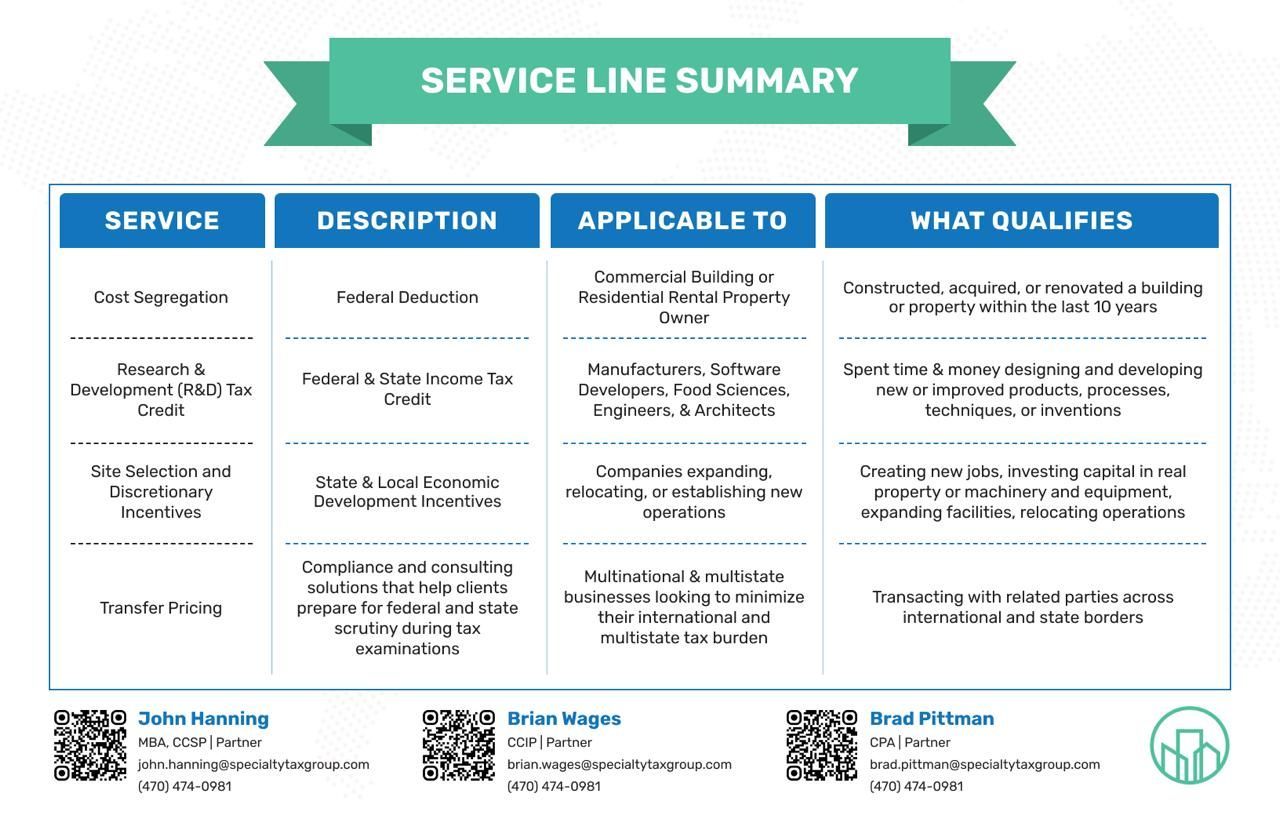
Speciality Tax Group (STG) is here to help your company maximize R&D tax benefits and adapt to the shifting tax landscape. Whether you're a startup or a large enterprise, our team of experts can assist with eligibility analysis, tax strategy, and compliance under H.R. 1990 and related laws.
Our comprehensive approach ensures you understand both the technical requirements and potential savings available through various tax credits, incentives, and deductions.
Contact STG today to protect your innovation strategy and reduce your tax burden.
2026 Tax Guide