This blog post has been researched, edited, and approved by John Hanning and Brian Wages. Join our newsletter below.
What’s New & Why It Matters
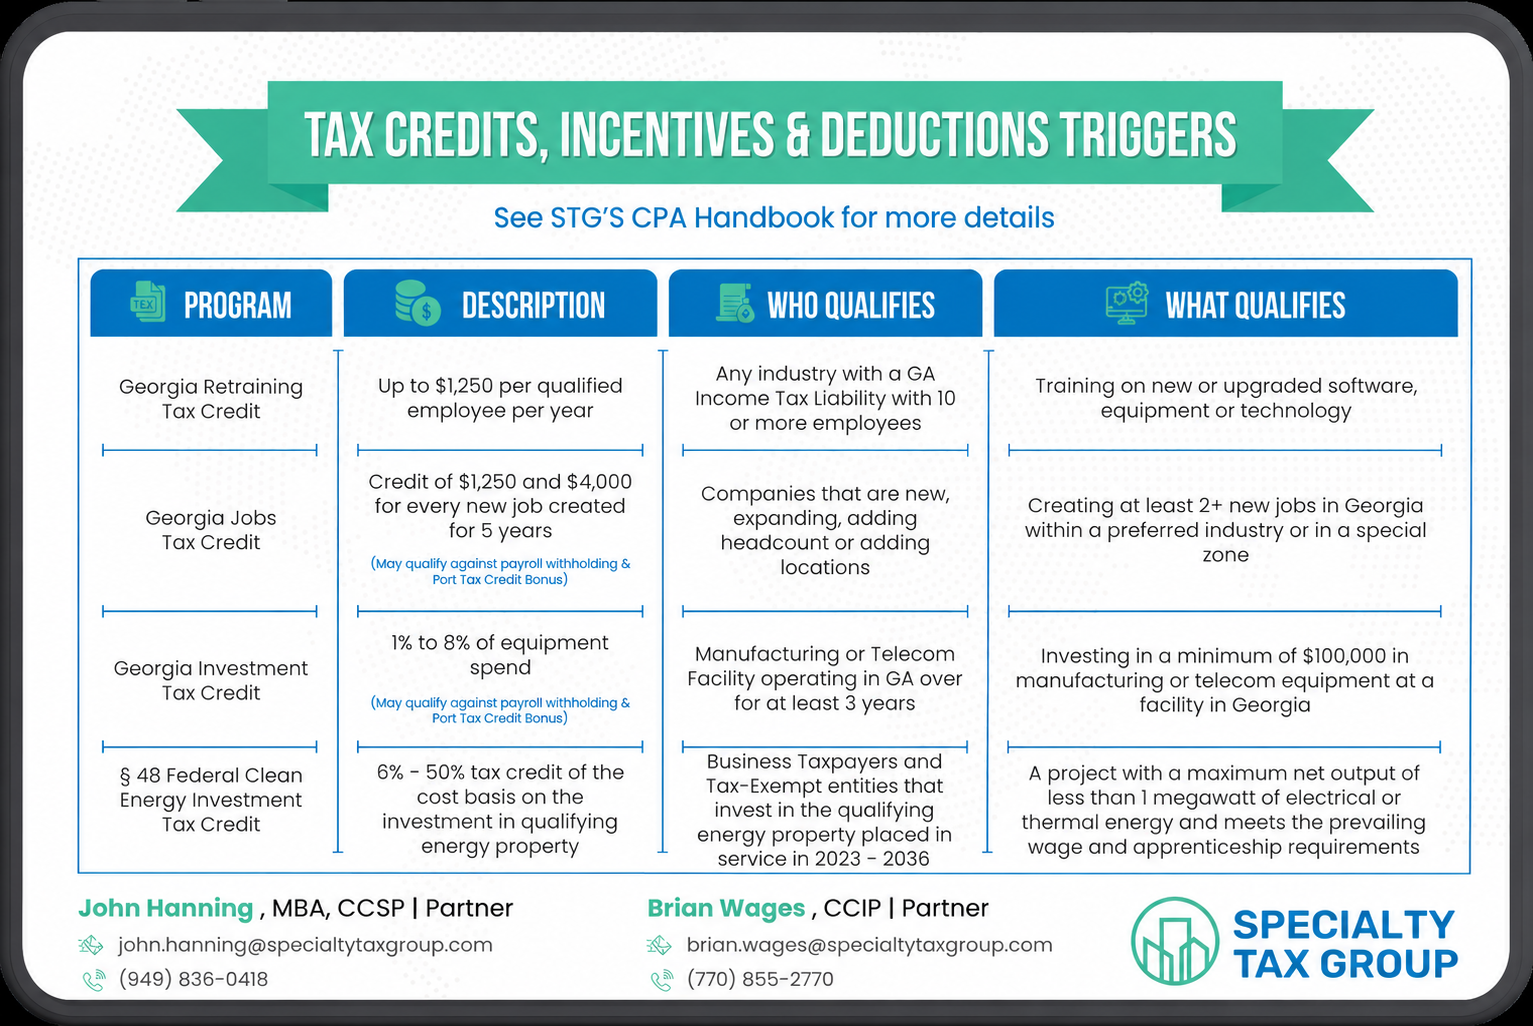
Georgia has extended the withholding election deadline for the R&D credit from 30 days to three years. This change gives businesses significantly more flexibility to monetize credits and improve cash flow. Companies now have time to plan strategically, rather than rushing decisions within a 30-day window. See official guidance here.
Key Takeaways
- Deadline extended from 30 days to 3 years for withholding election
- Businesses can use excess credits against payroll taxes
- Applies to all qualified research expenses
- 10% credit on qualified R&D spending above base amount
- Credits can offset up to 50% of income tax liability
- Unused credits carry forward for 10 years
Why This Change Matters
Previously, businesses had only 30 days after filing returns to elect withholding benefits. Many companies discovered they qualified for R&D credits months later, losing valuable opportunities. The new three-year window removes this barrier, enabling retroactive planning and better cash flow management.
This change makes Georgia's R&D program more competitive with other states.
Businesses gain time to understand their full credit benefits before making irrevocable elections.
Who Benefits Most from This Change?
Manufacturing, technology, biotech, and engineering firms stand to gain the most. These industries often incur significant R&D costs and may have unused credits. Startups and growing businesses with limited tax liability benefit from converting deferred credits into immediate payroll tax savings.
How the Georgia R&D Credit Works
Georgia’s R&D credit mirrors the federal program but includes state-specific benefits. Businesses calculate credits based on increased qualified research expenses above a base amount. The process involves determining the base amount, calculating current-year qualified expenses (wages, supplies, contractors), applying the 10% credit rate, and filing Form IT-RD with the Georgia income tax return.
Filing Requirements and Process Changes
Businesses must file Revenue Form IT-WH Notice of Intent through the Georgia Tax Center within the three-year statute of limitations after the due date of the Georgia income tax return. Electronic filing is mandatory, and the election can only be made once per tax year. File electronically here: https://dor.georgia.gov/it-wh-electronic-request-through-georgia-tax-center
Impact on Business Cash Flow
The extended deadline allows companies to optimize credit usage after reviewing full-year results. Benefits include immediate payroll tax reductions, better planning flexibility, and reduced compliance pressure. Businesses can apply excess credits against quarterly payroll taxes, improving liquidity throughout the year.
Frequently Asked Questions
Q: When does the new deadline apply?
A: It applies immediately and covers elections within three years of the original return due date.
Q: Can I amend prior elections?
A: Yes, if within the three-year statute of limitations.
Q: What forms are required?
A: Form IT-RD for the credit and Form IT-WH for withholding election. Access forms: https://dor.georgia.gov/tax-credits
Q: Does this affect federal credits?
A: No, this change applies only to Georgia state credits.
Next Steps for Businesses
· Review current R&D activities and identify qualifying expenses
· Assess payroll tax benefits and determine if withholding election makes sense
· Plan credit utilization to balance income tax offset with payroll benefits
· Consult professionals familiar with Georgia requirements for compliance
Contact Specialty Tax Group today for expert guidance on leveraging Georgia’s R&D credit and maximizing your tax benefits.
2024 Tax Guide